Tallahassee Homeowners Insurance
Buying a Tallahassee home or staring at a renewal that jumped? Send the address and we will compare available prices and coverage for that home, including the roof, trees, wind, flood, and deductibles that can change the quote.
Start with the address. We will help with the rest.
Buying? Add the closing date and any inspection reports. Renewing? Add the current policy or renewal. We will compare available options and show you where the coverage differs.
Buying: send the address, closing date, roof records, inspection reports, and lender deadline.
Tell us about mature trees, roof overhang, drainage, detached structures, and how the home will be occupied.
We check available insurers and unfinished requirements before you choose or switch.
Compare Tallahassee home insurance for a purchase or renewal
- Buying a Tallahassee or Leon County home: send the address and closing date so we can compare prices, coverage, lender details, and any roof, tree, inspection, occupancy, or flood questions before closing.
- Already own the home: send the declarations page or renewal so we can look for a better fit and show you where the coverage, deductibles, roof terms, or open requirements differ.
- The address matters. A historic home under mature canopy, a newer subdivision home, a rural Leon property, and a parent-owned home near campus do not raise the same underwriting questions.
- As an independent agency, we help Tallahassee and Leon County homeowners compare available insurers, policy terms, deductibles, and unfinished requirements for the property.
Leon County benchmark
$1,023
average premium per policy in Citizens' county report
Citizens personal residential data, reported August 31, 2026. A county benchmark, not a quote or a market average.
A County Benchmark Does Not Price Your Tallahassee Home
Citizens is Florida's state-created insurer of last resort. Its Leon County report is useful context, but it is not a target price for your house. Roof records, mature trees, older systems, drainage, occupancy, claims, rebuild cost, and the insurers willing to consider the address can move the answer.
Tallahassee quote prep
Want a faster Tallahassee price comparison?
Start with the address and tell us whether you are buying or renewing. Add the deadline, roof records, wind mitigation or 4-point report if available, and any flood, occupancy, or lender note.
What Changes a Tallahassee Home Insurance Quote?
We compare the actual home. The city name cannot tell us what the roof, trees, systems, flood map, occupancy, coverage, deductible, and insurer options will look like for your address.
Trees near the roof
Tallahassee's canopy is part of the city's character. Large limbs, overhang, tree condition, and the distance between the canopy and roof can also raise property and underwriting questions. We start with the actual home instead of treating every wooded lot alike.
Roof age, condition, and proof
The roof year, covering, permit, invoice, photos, and inspection comments can change which insurers will quote. Clear records can keep an uncertain roof date from changing the quote late in the process.
Older systems and 4-point reports
An older Tallahassee home may need clearer roof, electrical, plumbing, and HVAC information. A current 4-point report can answer those questions without pretending every insurer uses the same cutoff.
Flood maps and drainage
Tallahassee is inland, but heavy rain, low areas, creeks, lakes, and drainage can still matter. Standard homeowners insurance generally does not cover flood, so we keep the home policy and flood decision separate.
Rebuild cost and deductibles
Coverage A is based on the cost to rebuild, not the sale price or tax value. We also turn percentage hurricane deductibles into dollars so you can see the actual out-of-pocket exposure.
Occupancy, claims, and policy fit
Your primary home, a parent-owned home for a student, a second home, and a rental can need different policy treatment. Prior claims, detached structures, home businesses, and lender deadlines can change the comparison too.
Buying or renewing? Compare prices for the actual address.
Send the address and your deadline. Add the current policy, renewal, roof and permit details, inspection documents, tree or flood questions, occupancy, and lender information you already have.
Tallahassee's canopy changes the conversation
Put the Roof, Trees, and Wind on the Same Page
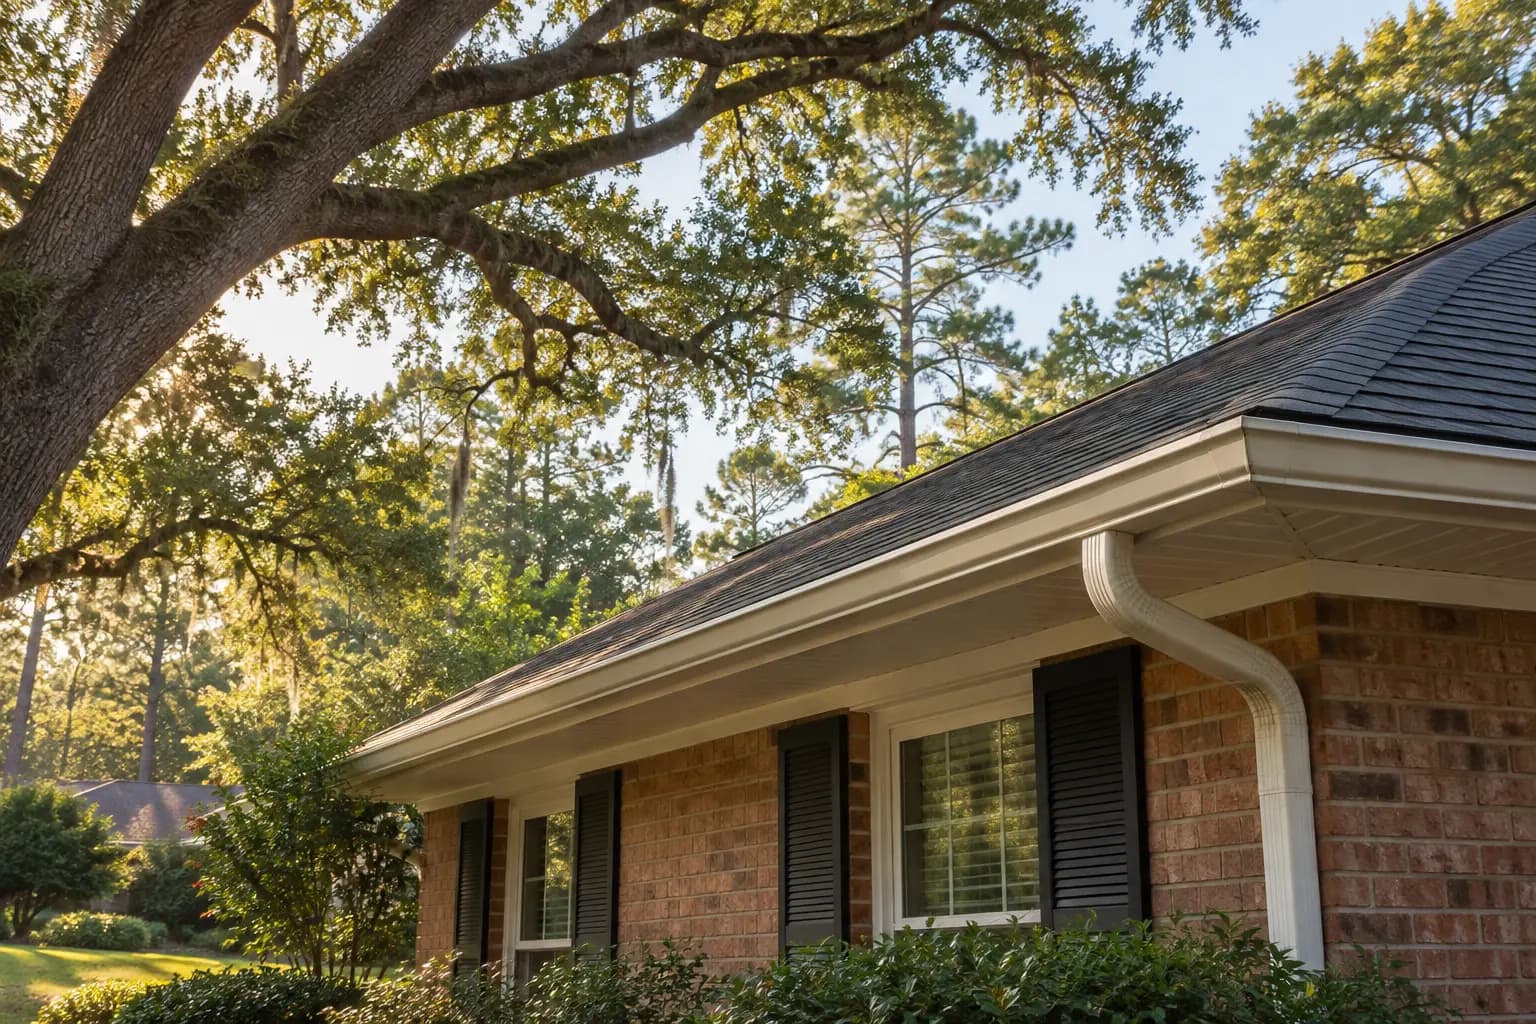
Tallahassee's urban-forest plan describes signature canopy roads, historic specimen trees, and large moss-draped oaks and pines. That canopy is part of what makes the city feel like home. It also means roof access, limb overhang, tree condition, wind, and prior repairs deserve a clear look before a quote is treated as finished.
We do not turn a tree-lined street into a blanket decline. We ask what is actually near the roof, what the inspection shows, and whether the insurer still needs photos, trimming, repair, or documentation.
Send roof permits, invoices, inspection comments, and clear exterior photos when you have them.
Tell us about large limbs over the roof, recent tree work, prior roof or water claims, and unfinished repairs.
Use a wind mitigation report to document roof shape, deck attachment, roof-to-wall connection, secondary water resistance, and opening protection.
Tallahassee Home Insurance Questions Change by Property
Neighborhood names help us ask better questions. They do not set the price or prove the flood, roof, tree, or occupancy answer.
Midtown, Betton Hills, Myers Park, and Los Robles
Older construction and renovation history can make roof permits, electrical, plumbing, HVAC, replacement cost, and 4-point questions more important. Mature trees make the property inspection and roofline worth a close look.
Killearn, Bradfordville, and northeast Leon County
Wooded lots, larger homes, additions, pools, detached structures, wells, septic systems, and longer driveways can add details that a generic city quote misses. The address and current property records still decide the questions.
Southwood, Southside, Woodville, and rural Leon County
Construction year, roof documentation, drainage, distance from fire protection, acreage, detached structures, and how the property is used can matter more than the neighborhood name.
Homes near FSU, FAMU, and TSC
Tell us who will live in the home. A student-owned or parent-owned primary residence, a second home, and a rental are not the same risk. We need the occupancy right before comparing policy forms.
Tallahassee Is Inland. Flood Maps Still Matter.
Standard homeowners insurance generally does not cover flood. Leon County notes that flood risk is not limited to mapped high-risk areas, and the City of Tallahassee points homeowners to separate building and contents coverage.
Check FEMA's current map for the address, then consider the lender requirement, local drainage, nearby creeks or lakes, elevation information, and what an uninsured water loss would mean for your budget.
Check the FEMA flood mapInland Does Not Mean Wind-Free
Tallahassee does not have the same coastal-surge exposure as a beach address, but hurricane wind, wind-driven rain, roof damage, and falling limbs can still affect a home. Review the roof and wind documents before comparing the deductible.
A percentage hurricane deductible is based on Coverage A. A 2% deductible on $400,000 of dwelling coverage is $8,000. We put the percentage and dollar amount side by side.
Understand hurricane deductiblesYour Tallahassee Renewal Went Up. Compare It Before You Cancel.
We want to see more than the new premium. We compare the coverage, deductible, roof and water terms, inspection questions, and price before you decide whether switching makes sense.
Read the Tallahassee renewal first
Premium, Coverage A, other structures, personal property, and loss-of-use limits
Hurricane and all-other-perils deductibles in both percentages and dollars
Roof settlement terms, water limits, exclusions, endorsements, and inspection notices
Renewal date, escrow timing, mortgage information, and any nonrenewal deadline
Clear the replacement before switching
Matching limits and deductibles instead of a lower price built on thinner coverage
Roof, electrical, plumbing, HVAC, photo, 4-point, and wind mitigation requirements
Effective date, payment, lender acceptance, and any unfinished repair requirements
Flood, trees, detached structures, student occupancy, rental use, and other separate questions
Confirm the replacement effective date, payment, lender details, and any unfinished inspection or repair requirements before canceling existing coverage.
Buying near FSU, FAMU, or TSC
Tell Us Who Will Live in the Home Before We Quote It
A parent buying a home for a student may describe the property as a second home, a student's primary home, or a rental. Those are not interchangeable. The policy form has to match the ownership, occupancy, and lease arrangement.
If the property will be rented to others, say that at the start. A true rental may need landlord or dwelling coverage instead of a standard owner-occupied homeowners policy.
Bring these answers before closing
Who owns the property and who will live there full time?
Will any room or unit be rented to someone outside the family?
Will the home be vacant before move-in or during school breaks?
Is there a lender deadline, lease, property manager, or association requirement?
Independent comparison
Which Home Insurance Companies May Fit a Tallahassee Address?
There is no one best company for every Tallahassee home. An insurer that likes a newer subdivision home may not quote an older roof under mature canopy. Another may consider the home but ask for an inspection, repairs, tree work, or different documentation.
We work with 31 carriers across our personal and commercial lines and compare the ones currently writing homes at your address. We look at the whole policy, not only the lowest number on the page.
Get Tallahassee PricesCompare these details before you choose
Dwelling, personal property, loss-of-use, and liability limits
Hurricane and all-other-perils deductibles in dollars
Roof settlement terms, water limits, and exclusions
Inspection, photo, repair, tree, or documentation conditions
Separate flood coverage and the lender's requirements
The exact effective date and any unfinished requirements
What to Send for a Tallahassee Home Insurance Quote
You do not need a perfect file before you start. Send what you have. We will tell you what is missing and what can wait.
Exact address and occupancy
Street address, ZIP code, who will live there, purchase or renewal date, lender deadline, and whether the property is a primary home, second home, parent-owned student home, rental, vacant property, or something else.
Current policy or renewal
Declarations page, renewal offer, Coverage A limit, hurricane and all-other-perils deductibles, roof terms, water limits, and mortgage information if there is a lender.
Roof and permit records
Roof year, material, permit, invoice, contract, inspection notes, repair receipts, and photos when the installation date or condition may be questioned.
Inspection and update records
Wind mitigation, 4-point, purchase inspection, roof certification, and documents for electrical, plumbing, HVAC, windows, or other major updates.
Flood and lender details
Flood-zone note, lender flood requirement, elevation certificate if available, mortgagee clause, loan number, and the date proof of coverage is due.
Claims and property features
Prior claims, tree or roof repairs, pool, pets, detached structures, home business, acreage, well or septic, rental use, or anything else that changes how the home is used.
Sources for Tallahassee Homeowners
We use current public sources for the county benchmark, canopy, flood, map, and deductible facts. Your quote still comes from the property and the insurers willing to consider it.
Citizens policies in force
Citizens publishes county-level personal residential policy counts and total premium. We use the August 31, 2026 Leon County report for the labeled benchmark on this page.
City of Tallahassee urban forestry
The city describes Tallahassee's signature canopy roads, historic specimen trees, and urban-forest planning. That local canopy is why tree condition, overhang, roof access, and wind deserve property-specific review.
Leon County flood information
Leon County explains that flood risk is not limited to mapped high-risk areas and points residents to separate building and contents coverage.
City of Tallahassee flood insurance
The city explains that standard homeowners policies do not cover flood and that flood can damage both the building and its contents.
FEMA Flood Map Service Center
Official address-level flood-map lookup. A map is useful context, but the lender and flood insurer may still need more property information.
Florida DFS homeowners overview
Florida consumer guidance on homeowners coverage, inspections, underwriting, rates, discounts, and questions to ask when comparing policies.
Florida hurricane-deductible law
Florida Statutes section 627.701 covers hurricane deductibles and required policy disclosures. Your declarations page shows the deductible that applies to your policy.
Tallahassee Home Insurance Resources
Florida Home Insurance
Our statewide homeowners page explains the quote path, coverage questions, and address-first comparison process for homes anywhere in Florida.
Florida Home Insurance Quote Checklist
A practical list of the property, roof, inspection, lender, claims, and policy details that can speed up a home quote.
Florida Home Insurance Inspection Guide
How 4-point, wind mitigation, roof, purchase, and insurer inspections fit into a Florida home quote or renewal.
Florida Roof Age and Home Insurance
Roof age, permits, inspection proof, shingle and metal roof questions, and roof settlement terms before you switch.
Florida Wind Mitigation Discounts
What a wind mitigation inspection documents and how roof shape, connections, deck attachment, and opening protection can affect credits.
Florida Hurricane Deductibles
How hurricane deductibles work, when they apply, and why the percentage should always be translated into a dollar amount.
Florida Home Insurance by County
Statewide county context with carefully labeled source data, including the limits of using county figures for an individual home.
Flood Insurance
Compare NFIP and private flood options when the address, lender, flood map, or drainage concern calls for separate protection.
Tallahassee Homeowners Insurance FAQ
Straight answers for buying, renewing, comparing, and preparing your home-insurance documents.
Ready to see which home insurance options fit?
Send the address and tell us whether you are buying, renewing, or dealing with a nonrenewal. Add the current policy, roof records, inspection reports, occupancy, tree or flood concerns, and lender deadline you already have.