St. Augustine Homeowners Insurance
Buying a St. Augustine home or staring at a renewal that jumped? Send the address and we will compare available prices and coverage for that property, including the flood, wind, roof, rebuild cost, and deductibles that can change the quote.
Start with the address. We will help with the rest.
Buying? Add the closing date and any inspection reports. Renewing? Add the current policy or renewal. We will compare available options and show you where the coverage differs.
Buying: send the address, closing date, roof records, inspection reports, and lender deadline.
Add the flood-zone note, elevation certificate, or current flood declaration if you have one.
We check available insurers and unfinished requirements before you choose or switch.
Compare St. Augustine home insurance for a purchase or renewal
- Buying a St. Augustine or St. Johns County home: send the address and closing date so we can compare prices, coverage, lender details, and any flood, wind, roof, inspection, or elevation questions before closing.
- Already own the home: send the declarations page or renewal so we can look for a better fit and show you where the coverage, deductibles, roof terms, or open requirements differ.
- The address and construction matter. A historic downtown property, barrier-island home, beach address, and newer master-planned home do not raise the same underwriting questions.
- As an independent agency, we help St. Augustine and St. Johns County homeowners compare available insurers, policy terms, deductibles, and unfinished requirements for the property.
St. Johns County benchmark
$1,374
average premium per policy in Citizens' county report
Citizens August 31, 2026 personal residential multiperil (PR-M): 811 St. Johns County policies and $1,114,033 in premium, excluding takeouts. We divided those totals and rounded to $1,374 per policy. This is insurer-of-last-resort county context, not a voluntary-market average, quote, target, minimum, or price floor.
A County Benchmark Does Not Price Your St. Augustine Home
Citizens is Florida's state-created insurer of last resort. Its St. Johns County report is useful context, but it is not a target price for your house. Flood and wind exposure, elevation, roof records, construction, occupancy, claims, rebuild cost, and the insurers willing to consider the address can move the answer.
Across our personal and commercial lines, we work with 31 carriers. For a St. Augustine home, we compare the private insurers currently writing in St. Johns County. An eligible private-market option often comes in lower than Citizens, but we still line up coverage, deductibles, inspections, and open requirements before recommending a switch.
St. Augustine quote prep
Want a faster St. Augustine price comparison?
Start with the address and tell us whether you are buying or renewing. Add the deadline, roof records, wind mitigation or 4-point report, elevation certificate if available, and any flood, occupancy, or lender note.
What Changes a St. Augustine Home Insurance Quote?
We compare the actual home. The city name cannot tell us what the flood and wind context, elevation, roof, construction, systems, rebuild cost, occupancy, deductible, and insurer options will look like for your address.
Flood, storm surge, and elevation
Standard homeowners insurance generally does not cover flood. The address, FEMA map, local floodplain information, lender requirement, and any elevation certificate belong in a separate flood review.
Roof age, construction, and proof
A historic masonry or coquina-area home and a newer community home may reach different insurers. Roof year, covering, permits, updates, photos, and inspection notes help us present the property accurately.
4-point, wind, and elevation records
A 4-point report answers roof, electrical, plumbing, and HVAC questions. Wind mitigation records may document eligible features, while an elevation certificate can help with a separate flood quote.
Coastal wind and hurricane deductibles
Distance to the coast, roof shape, opening protection, and other wind features can affect eligibility and price. We translate a percentage hurricane deductible into dollars before you choose.
Replacement cost and home features
Coverage A is based on the estimated cost to rebuild, not the sale price or tax value. Size, finishes, construction, labor, materials, and custom or historic features all affect the estimate.
Occupancy, claims, and policy fit
A primary home, second home, rental, short-term rental, vacant property, or home under renovation may need a different policy path. Claims, lender deadlines, and open conditions can change the comparison too.
Buying or renewing? Compare prices for the actual address.
Send the address and your deadline. Add the current policy or renewal, roof and permit details, inspection documents, flood or elevation information, occupancy, and lender details you already have.
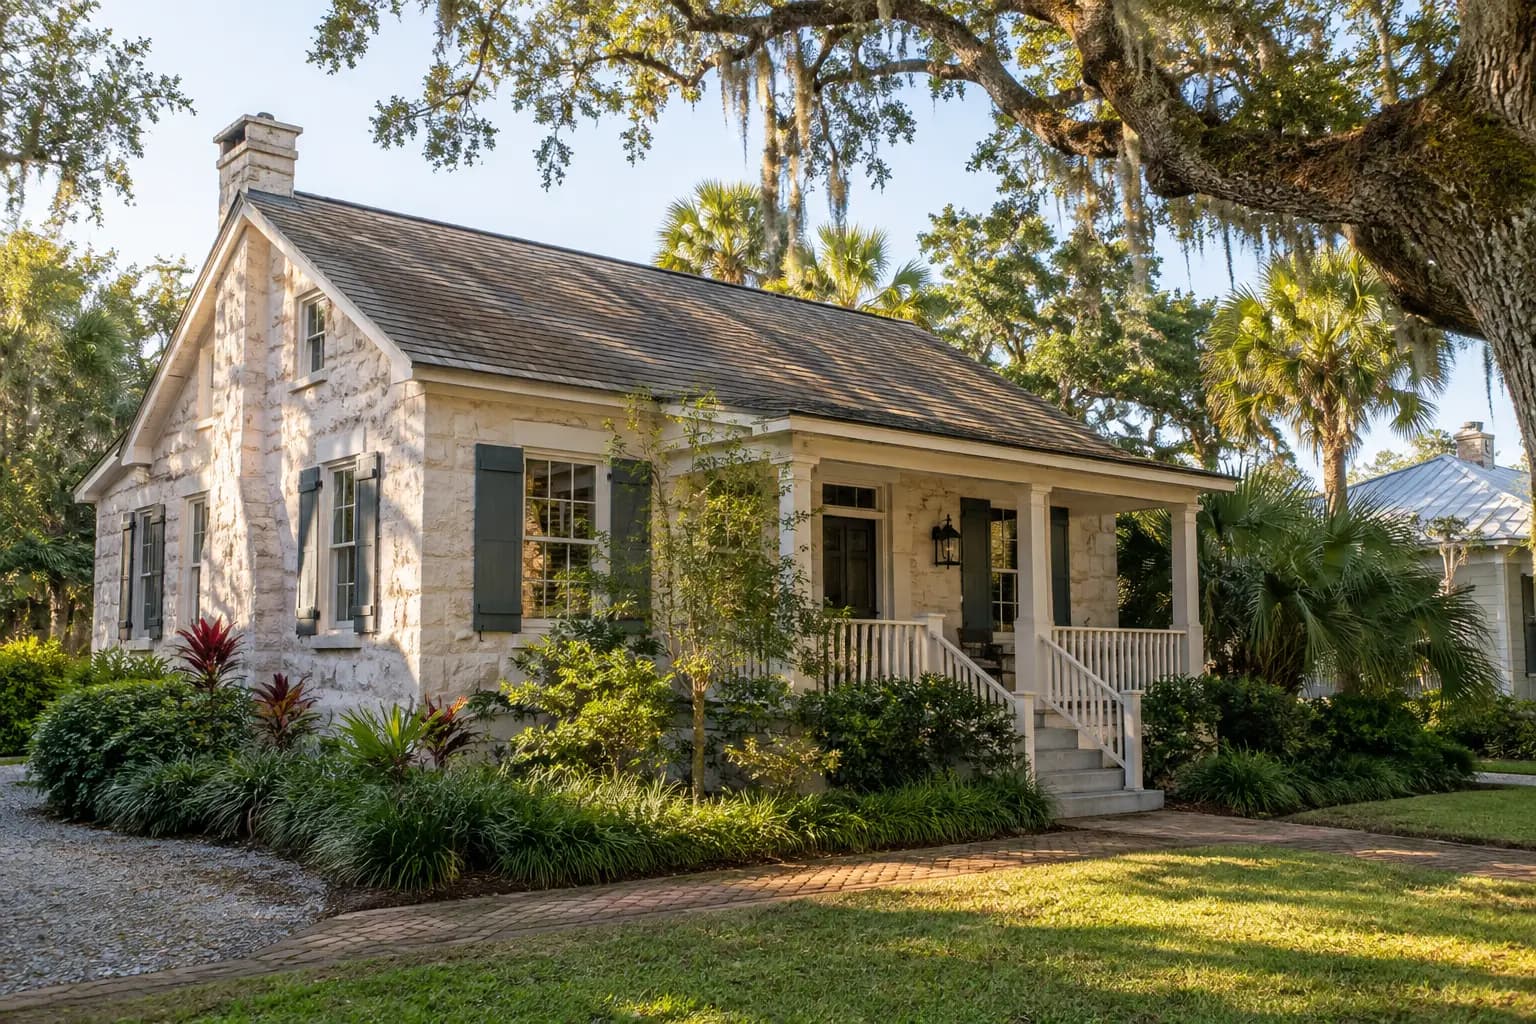
Historic and newer homes quote differently
Old St. Augustine and New St. Johns Need Different Property Details
A historic masonry or coquina-area home can need detailed roof, electrical, plumbing, HVAC, permit, condition, and elevation records. Its custom materials and workmanship can also make the replacement estimate more involved than the sale price suggests.
Newer homes in Nocatee, World Golf Village, and other growing communities may have clearer construction and wind records. That can change the quote conversation, but it does not erase flood, occupancy, claims, rebuild-cost, deductible, or lender questions.
For an older home, send permits and update records instead of relying on an estimated year.
For any home, make sure the rebuild estimate reflects the construction and finishes actually present.
Use flood and elevation records for the address; a community name cannot settle the risk or coverage question.
St. Augustine Home Insurance Questions Change by Property
Neighborhood names help us ask better questions. They do not set the price or prove the roof, wind, flood, elevation, construction, replacement-cost, or occupancy answer.
Historic downtown and older St. Augustine homes
Very old masonry, coquina-area, and renovated homes may need clearer roof, electrical, plumbing, HVAC, permit, elevation, and rebuild details. The actual updates and condition matter more than the age label alone.
Anastasia Island and St. Augustine Beach
Barrier-island and near-water addresses deserve a close flood, storm-surge, wind, roof, hurricane-deductible, and elevation review. Homeowners and flood coverage remain separate decisions.
Vilano Beach and Ponte Vedra Beach
Coastal location can narrow the market. We still need the roof and wind records plus the flood-zone and elevation context. Construction details and replacement cost matter too. A neighborhood name never replaces the property records or address-level map check.
Nocatee, World Golf Village, and newer communities
Newer construction may bring better roof and wind records than an older city home, but it does not make flood, rebuild cost, claims, occupancy, lender, or deductible questions disappear. We still quote the exact property.
Flood and Storm Surge Need Their Own Coverage Review
Standard homeowners insurance generally does not cover flood. Heavy rain, high tides, storm surge, drainage, and coastal or tropical storms can create address-specific flood questions in St. Augustine and St. Johns County.
The City documents that Hurricane Matthew flooded Davis Shores, Lincolnville, the Historic Districts, and Abbott Tract. Hurricane Irma affected many of the same areas. That history is useful context, but it does not determine the risk at a specific address.
Check FEMA and county tools for the address, then compare NFIP or private flood options. A lender's requirement is one part of the decision; the separate policy, limits, contents coverage, waiting period, and effective date still matter.
Check St. Johns County flood resourcesCoastal Wind and Flood Are Related Risks, Not One Policy
Homeowners coverage can address covered wind damage, subject to the policy terms and deductible. It does not turn into flood coverage because the same storm also brings surge or rising water. Keep both decisions visible when comparing options.
Review the roof and wind documents, confirm any mitigation credits, and turn the percentage hurricane deductible into dollars. A 2% deductible on $500,000 of Coverage A is $10,000.
Read Florida's hurricane-deductible lawYour St. Augustine Renewal Went Up. Compare It Before You Cancel.
We want to see more than the new premium. We compare the coverage, deductible, roof and water terms, inspection questions, and price before you decide whether switching makes sense.
Read the St. Augustine renewal first
Premium, Coverage A, other structures, personal property, and loss-of-use limits
Hurricane and all-other-perils deductibles in both percentages and dollars
Roof settlement terms, water limits, exclusions, endorsements, and inspection notices
Renewal date, escrow timing, mortgage information, and any nonrenewal deadline
Clear the replacement before switching
Matching limits and deductibles instead of a lower price built on thinner coverage
Roof, electrical, plumbing, HVAC, photo, 4-point, and wind mitigation requirements
Effective date, payment, lender acceptance, and any unfinished repair requirements
Separate flood coverage, elevation records, detached structures, rental use, and other property-specific questions
Confirm the replacement effective date, payment, lender details, and any unfinished inspection or repair requirements before canceling existing coverage.
Insure the rebuild, not the listing price
Replacement Cost Deserves a Closer Look in St. Johns County
Higher sale prices do not automatically set the dwelling limit. Coverage A is built from an estimate of what it would take to reconstruct the home with current labor, materials, size, finishes, construction, and local building requirements.
That distinction matters for a custom coastal home, a historic building with unusual materials, and a newer home with upgraded finishes. We compare the estimate and policy terms instead of treating the purchase price, tax value, and rebuild cost as the same number.
See Florida homeowners coverage basicsBring these property answers before we quote
What are the square footage, construction type, number of stories, roof shape, exterior materials, and foundation?
Are there custom interiors, historic materials, upgraded kitchens, porches, pools, garages, or detached structures?
Does the estimate account for current labor and material costs rather than the sale price or land value?
Do the dwelling limit, extended replacement terms, ordinance or law coverage, and deductible make sense together?
Independent comparison
Which Home Insurance Companies May Fit a St. Augustine Address?
There is no one best company for every St. Augustine home. An insurer that likes a newer inland community home may not quote an older roof or the same coastal address. Another may consider the property but ask for an inspection, repairs, elevation details, or different documentation.
We work with 31 carriers across our personal and commercial lines and compare the ones currently writing homes at your address. We look at the whole policy, not only the lowest number on the page.
Get St. Augustine PricesCompare these details before you choose
Dwelling, personal property, loss-of-use, and liability limits
Hurricane and all-other-perils deductibles in dollars
Roof settlement terms, water limits, and exclusions
Inspection, photo, repair, elevation, or documentation conditions
Separate flood coverage and the lender's requirements
The exact effective date and any unfinished requirements
What to Send for a St. Augustine Home Insurance Quote
You do not need a perfect file before you start. Send what you have. We will tell you what is missing and what can wait.
Exact address and occupancy
Street address, ZIP code, who will live there, purchase or renewal date, lender deadline, and whether the property is a primary home, second home, rental, vacant property, or something else.
Current policy or renewal
Declarations page, renewal offer, Coverage A limit, hurricane and all-other-perils deductibles, roof terms, water limits, and mortgage information if there is a lender.
Roof and permit records
Roof year, material, permit, invoice, contract, inspection notes, repair receipts, and photos when the installation date or condition may be questioned.
Inspection and update records
Wind mitigation, 4-point, purchase inspection, roof certification, and documents for electrical, plumbing, HVAC, windows, or other major updates.
Flood and lender details
Flood-zone note, lender flood requirement, elevation certificate if available, current flood declaration, mortgagee clause, loan number, and the date proof of coverage is due.
Claims and property features
Prior claims, pool, pets, detached structures, historic or custom features, rental or short-term-rental use, renovation, vacancy, or anything else that changes how the property is used.
Sources for St. Augustine Homeowners
We use current public sources for the county benchmark, flood, historic-building, hurricane-deductible, and map facts. Your quote still comes from the property and the insurers willing to consider it.
Citizens policies in force
Citizens' August 31, 2026 St. Johns County personal residential multiperil report lists 811 policies and $1,114,033 in premium, excluding takeouts. The $1,374 figure on this page is derived from those totals and rounded.
St. Johns County Floodplain Facts
County resources include address and parcel flood-zone tools, storm-surge context, elevation-certificate help, and official floodplain contacts. A map is context, not a coverage determination.
FEMA Flood Map Service Center
FEMA's official address-level map lookup shows the current map panel and flood-zone context. Lenders and flood insurers may still need additional property information.
City of St. Augustine flood insurance
The city explains that most homeowners policies do not cover flood, that NFIP coverage is separate, and that a waiting period can apply. Policy and effective-date details still control.
Flood guidance for historic properties
St. Augustine's official guidance addresses flood planning for historic properties. It is useful context for older buildings, not a substitute for an insurer, lender, or preservation review.
Florida DFS homeowners overview
Florida consumer guidance covers homeowners insurance, underwriting, inspections, mitigation, and questions to ask while comparing policies.
Florida hurricane-deductible law
Florida Statutes section 627.701 covers hurricane deductibles and required disclosures. The declarations page and policy show the deductible and terms that apply.
City of St. Augustine Flood Hazards
The city documents that Hurricane Matthew flooded Davis Shores, Lincolnville, the Historic Districts, and Abbott Tract, and that Hurricane Irma affected many of the same areas. That history does not determine the risk at a specific address.
St. Augustine Home Insurance Resources
Florida Home Insurance
Our statewide homeowners page explains the quote path, coverage questions, and address-first comparison process for homes anywhere in Florida.
Florida Home Insurance Quote Checklist
A practical list of the property, roof, inspection, lender, claims, and policy details that can speed up a home quote.
Florida Home Insurance Inspection Guide
How 4-point, wind mitigation, roof, purchase, and insurer inspections fit into a Florida home quote or renewal.
Florida Roof Age and Home Insurance
Roof age, permits, inspection proof, shingle and metal roof questions, and roof settlement terms before you switch.
Florida Wind Mitigation Discounts
What a wind mitigation inspection documents and how roof shape, connections, deck attachment, and opening protection can affect credits.
Florida Hurricane Deductibles
How hurricane deductibles work, when they apply, and why the percentage should always be translated into a dollar amount.
Florida Home Insurance by County
Statewide county context with carefully labeled source data, including the limits of using county figures for an individual home.
Flood Insurance
Compare NFIP and private flood options when the address, lender, flood map, or drainage concern calls for separate protection.
St. Augustine Homeowners Insurance FAQ
Straight answers for buying, renewing, comparing, and preparing your home-insurance documents.
Ready to see which home insurance options fit?
Send the address and tell us whether you are buying, renewing, or dealing with a nonrenewal. Add the current policy, roof and construction records, inspection reports, occupancy, flood or elevation details, and the lender deadline you already have.