Boat & Watercraft Insurance on the Suwannee River: A Guide for North Florida Boaters
Suwannee River boat insurance guide for North Florida boaters: liability, hull, trailer, towing, jon boats, pontoons, and what to send for pricing.

Jenna Greene
Licensed Insurance Agent
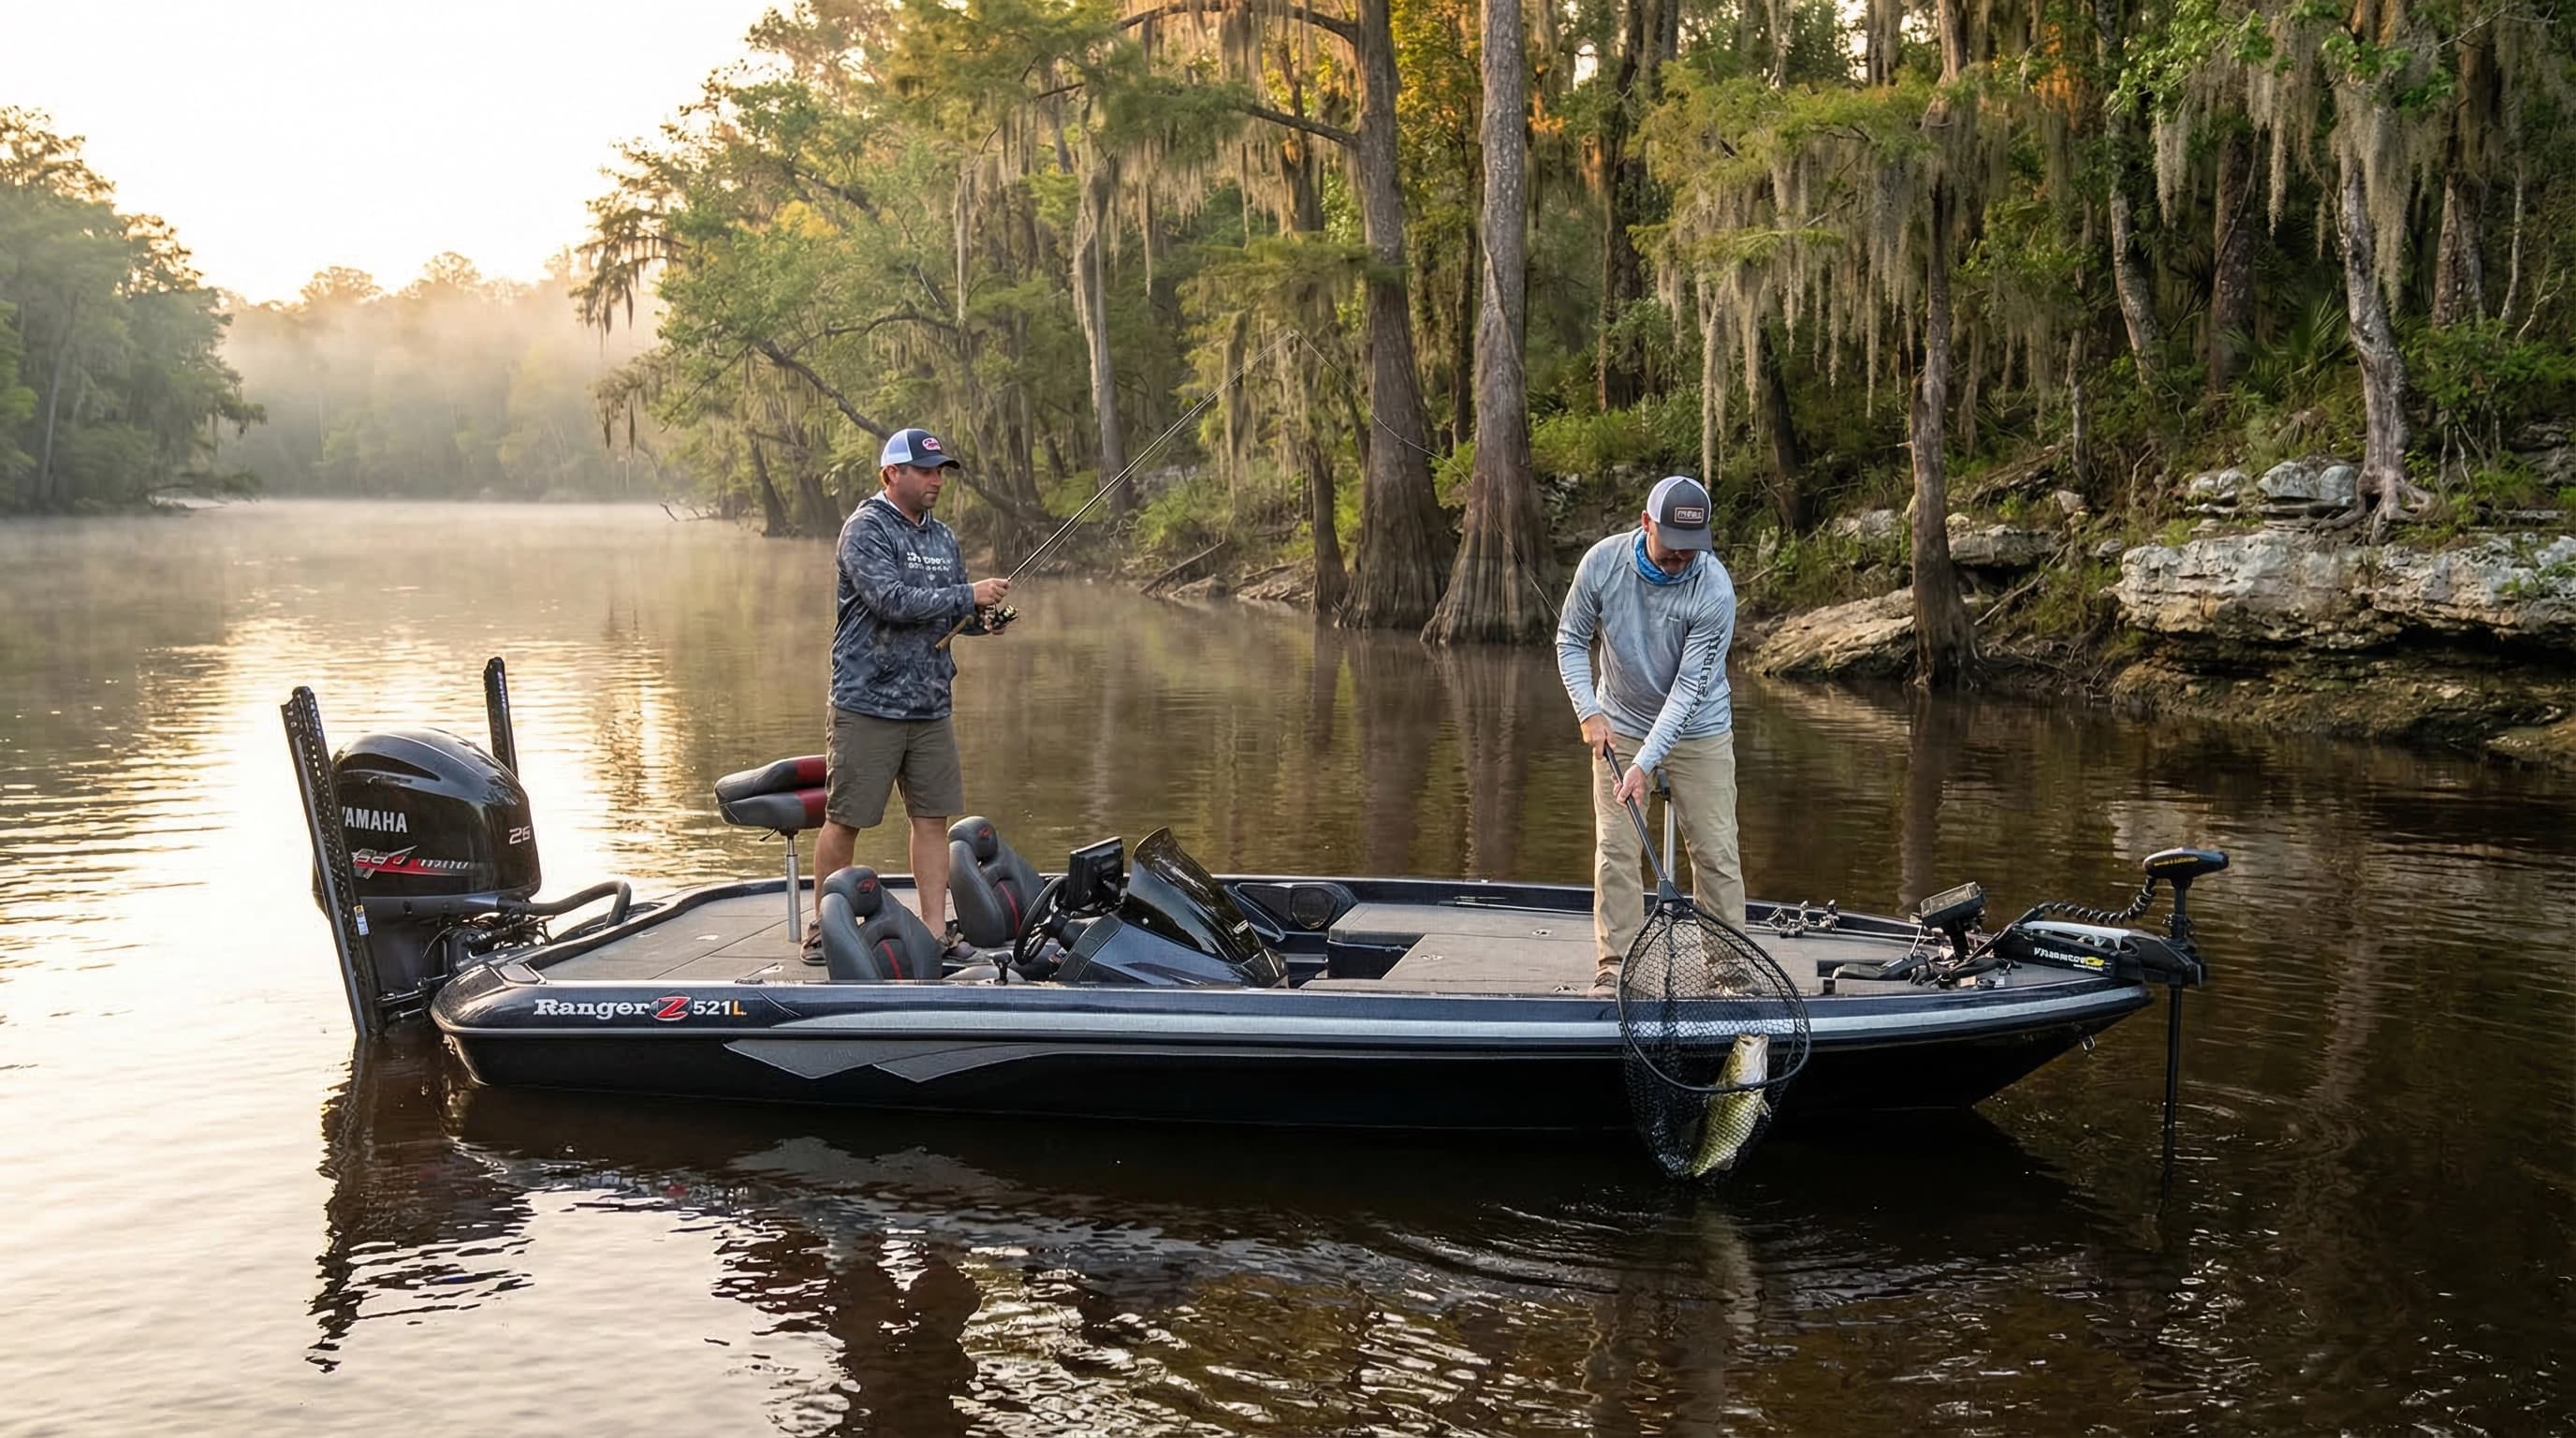
If you've spent any time on the Suwannee River, the Ichetucknee, the Santa Fe, or any of the spring runs that feed these waters in Suwannee and Columbia Counties, you know what makes this part of Florida special. Dark, tannin-stained water reflecting ancient cypress. Bass holding in the shallows. The kind of fishing and paddling that doesn't require a three-hour drive to the coast.
It also requires a boat, and if you are running anything from a jon boat with a trolling motor to a fully rigged bass boat or pontoon, it is worth comparing watercraft coverage built around that vessel. Lenders, marinas, leases, and other contracts may set their own requirements, while the right property and liability options can help with covered damage or an accident.
Here's what North Florida boaters need to know.
Key Takeaway
Fast answer: homeowners policy treatment varies by boat type, horsepower, value, ownership, use, and policy form. A separate watercraft quote lets us compare hull, motor, trailer, liability, medical payments, uninsured boater, towing, and navigation territory together.
Does Your Existing Insurance Cover Your Boat?
The short answer: it depends on the boat and the policy.
Homeowners insurance: A homeowners policy may include limited protection for certain small boats, but the sublimits and liability restrictions vary. A bass boat, pontoon, personal watercraft, higher-horsepower motor, or higher-value rig may need separate coverage. Check the property sublimit, horsepower rules, liability wording, trailer treatment, and endorsements on the actual form.
Auto insurance: Treatment of a boat trailer and liability while towing depends on the auto policy. The boat, motor, trailer physical damage, and watercraft liability should each be checked rather than assumed.
Possible gap: Theft, sinking, collision, and liability may be restricted or excluded under existing home and auto policies. Comparing a watercraft quote shows which losses, limits, deductibles, and navigation areas are actually included.
Compare Watercraft Liability
Florida generally does not require insurance for your own recreational boat. A lender or marina may require it, and boat rentals or commercial use need a separate look. Liability coverage can help with the cost of injuries or damage you cause on the water, whether a policy is required or not.
Progressive explains Florida recreational-boat insurance requirements. If you rent boats to others, check the separate FWC livery requirements.
What Watercraft Insurance Covers
A boat and watercraft insurance policy may offer several coverage options:
Physical Damage (Hull Coverage)
Available physical damage coverage may address losses involving:
- Collision with another vessel, dock, or submerged object
- Capsizing or sinking
- Fire, theft, and vandalism
- Weather damage (lightning, hail, windstorm)
- Transport accidents (your boat falling off the trailer on US-129)
Agreed value generally bases a covered total-loss payment on the boat value set in your policy. Actual cash value reflects the boat's value when the loss happens, including depreciation. Partial-loss repairs, deductibles and items such as motors or trailers still need a closer look. Chubb's boat insurance guide explains why the settlement method matters. We can compare those terms alongside the price.
Liability Coverage
May address covered bodily injury or property damage for which an insured is legally responsible, along with defense costs provided by the form. Compare available limits, exclusions, operator restrictions, and any umbrella requirements with the rest of the household's coverage.
Medical Payments
May help with covered medical expenses for an insured or passengers after a boating accident. Limits, eligible people, and interaction with liability coverage depend on the form.
Uninsured/Underinsured Boater Coverage
This option may apply when an insured is injured by an uninsured or underinsured boater, subject to the policy terms, limits, and eligibility rules.
Towing and Assistance
Optional on-water towing or assistance may help with a covered breakdown or grounding. Check the service area, limit, reimbursement terms, and whether the boat's river navigation territory is included.
Have a jon boat, bass boat, pontoon, personal watercraft, or river boat near Live Oak, Branford, or Lake City? Send the boat, motor, trailer, storage, and operator details and we will check the watercraft options.
Boating on the Suwannee River: What You Should Know
The Suwannee River presents some specific conditions that boaters and their insurers need to understand.
Submerged hazards: The Suwannee is a natural river where logs, rocks, and sandbars can become hazards, particularly during lower water levels. Ask how the quote treats collision with a submerged object and damage caused by wear, deterioration, or repeated shallow-water contact.
Variable water levels: River level can change significantly based on rainfall upstream in Georgia and throughout the North Florida watershed. Areas that are navigable at high water become shallow and hazardous at low water.
Spring runs and tributaries: The spring systems feeding the Suwannee — including several first-magnitude springs in Suwannee County — attract significant boating and snorkeling activity. High traffic areas around popular springs can increase collision risk.
Remote stretches: Parts of the Suwannee corridor in Suwannee and Columbia Counties are quite remote. A breakdown in a remote section means a longer tow — another reason on-water towing coverage matters.
Key Takeaway
If you regularly run on the Suwannee River system, ask how each quote treats collision with submerged objects. Also compare exclusions for wear, deterioration, and repeated shallow-water contact so the difference between sudden covered damage and maintenance is clear.
What Does Boat Insurance Cost in Suwannee County?
The price varies with the vessel, motor, trailer, storage, operator history, navigation territory, selected coverage, limits, and deductibles.
Boat Insurance Quote Factors for Suwannee County Boaters
Factors that affect your rate:
- Boat value and type
- Engine horsepower
- Your boating experience and safety course completion
- Whether the boat is stored at home, at a marina, or in water
- Your navigation territory (inland rivers vs. coastal/offshore)
- Prior claims history
- Trailer value and whether the trailer needs physical damage coverage
- Agreed value vs. actual cash value settlement
Your boat's details give us a useful starting point for pricing. Send the year, make/model, approximate value and how you use it. If you do not have every motor or trailer detail handy, contact us and we can help you work through the rest.
Boat Insurance Discounts to Ask About
Discounts and rating credits vary by carrier and policy. Ask whether the current quote considers an approved boating safety course, operator experience, bundling, storage, seasonal or lay-up periods, payment method, or protective equipment. The Florida Fish and Wildlife Conservation Commission boating regulations page summarizes current Florida boating safety and education rules; the carrier determines whether a course affects the price.
What About Kayaks, Canoes, and Paddleboards?
The Suwannee and Ichetucknee Rivers are also popular for paddling — kayaks, canoes, and stand-up paddleboards are all common. Homeowners policy treatment depends on the item's value, use, storage, and form, so check the personal-property limit and liability wording.
For a higher-value touring kayak or canoe, ask whether it should be scheduled, endorsed, or insured separately and how the policy applies on waterways with motorboat traffic.
Let us compare the lowest available boat price with motor, trailer, submerged-object damage, towing, and liability options before boating season gets busy.
Insuring Your Boat in Live Oak and Suwannee County
For boaters in Suwannee County, our Live Oak insurance page explains how we help nearby families from our Lake City office. Compare coverage and start a quote on our boat and watercraft insurance page. If you also own an RV, motorcycle, or golf cart, our motorcycle and RV insurance page can help you compare recreational coverage together.
Our office can review watercraft of all kinds for boaters in Suwannee County, Columbia County, and across North Central Florida. Whether you're running a jon boat on the lower Suwannee near Branford, fishing the spring runs near Ichetucknee, or keeping a pontoon on the river near Live Oak, we can compare coverage around your vessel and your boating habits.
Call 1-800-252-6885 or send the boat details online. We will review hull, motor, trailer, storage, liability, towing, and river-use exposure before recommending a watercraft quote.
Suwannee River Boat Insurance FAQ
Does homeowners insurance cover my boat on the Suwannee River?
Homeowners policy treatment of a boat depends on the form, vessel type, horsepower, value, ownership, and use. Some policies provide limited watercraft property or liability coverage, while others exclude or restrict it. Compare the exact sublimits, exclusions, and available endorsements before relying on the home policy for a bass boat, pontoon, motor, or trailer.
Is watercraft insurance required for boating on the Suwannee River in Florida?
Florida generally does not require insurance for a privately owned boat used for recreation. A lender, marina or lease can still require coverage, and rental or other commercial use follows different rules. Even when insurance is optional, liability coverage can help protect you if you cause an injury or damage another boat. Tell us how you use and store your boat so we can compare the right options.
What does boat insurance cover for Suwannee River boaters?
A watercraft policy may offer physical damage for the hull, motor, and trailer; liability; medical payments; uninsured boater coverage; and on-water towing. The selected coverages, navigation territory, submerged-object treatment, limits, deductibles, and exclusions determine how the policy applies, so compare those terms on the actual quote.
What is the difference between agreed value and actual cash value for boat insurance?
Agreed value generally uses the boat value set in the policy for a covered total loss. Actual cash value reflects its value at the time of the loss, including depreciation. Partial-loss repairs and deductibles can work differently, even on an agreed-value policy. We can compare the settlement terms alongside the premium so you know what you are buying.
How much does boat insurance cost in Suwannee County, FL?
The price depends on boat type, value, hull length, motor horsepower, trailer value, storage, navigation territory, operator history, prior claims, liability limit, and whether the policy is agreed value or actual cash value. Send the year, make/model, value, motor details, trailer details, storage location, and how you use the boat so our office can compare available watercraft coverage and prices.
Personal Insurance Team Leader
Jenna Greene has worked in Florida personal insurance since 2011 and holds an active Florida 20-44 Personal Lines Agent license. She leads personal insurance quoting standards, renewal retention, carrier relationships, and market availability at Greene & Associates, with deep experience in homeowners, high-value homes, manufactured homes, flood, and personal auto. FL License #W055787.
jenna@greeneinsurance.comReady to Get Covered?
Our licensed agents compare carrier options, coverage, and price, then help you choose.